Consumer Guide | Comparing Car Insurance Malaysia 2026 - 2027
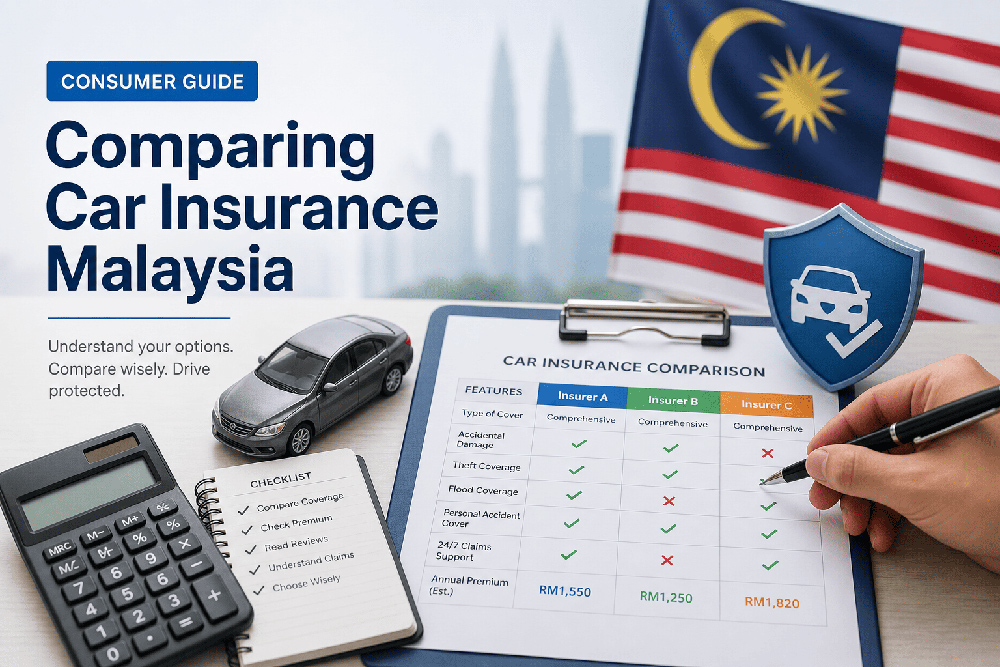
Every year, millions of Malaysians renew their motor road tax, and with it, their motor insurance. But did you know that since the implementation of the phased liberalisation of motor insurance in Malaysia, the premium you pay can vary depending on your individual risk profile? This means the premium you pay may differ on how your individual risk is assessed, while giving flexibility to explore and compare different motor insurance options that balance your driving habits, vehicle age and budget.
With more options available, understanding your coverage can help you make more informed decisions when it’s time to renew/purchase your insurance policy. Here is the official PIAM consumer guide to help you effectively compare car insurance policies, so you can choose the right coverage that best suits your needs and budget.
Do You Really Need Comprehensive Coverage In Malaysia
Under the Road Transport Act 1987, it is a legal offense to drive a motor vehicle without basic insurance coverage. When you request a quote, you’ll typically encounter three main levels of coverage. Choosing the right one is the foundation of your financial protection on the road:
| Feature / Coverage Type | Third-Party Only | Third-Party, Fire & Theft (TPFT) | Comprehensive Car Insurance |
|---|---|---|---|
| Legal minimum required for Road Tax? | Yes | Yes | Yes |
| Injury or death to other parties? | Yes | Yes | Yes |
| Damage to other people's property/car? | Yes | Yes | Yes |
| Your car stolen? | No | Yes | Yes |
| Your car catches fire? | No | Yes | Yes |
| Accidental damage to your own car due to collision and overturning or impact damage by falling objects? | No | No | Yes |
1. Third-Party Cover: While “Act” Cover is the absolute bare minimum required by law the minimum cover commonly purchased in the market is Third Party which pays for bodily injuries or property damage caused to other people in an accident where you are at fault.
2. Third-Party, Fire and Theft (TPFT): This offers the above mentioned baseline third-party protection but adds a safety net if your vehicle is stolen or destroyed by an accidental fire.
3. Comprehensive Car Insurance: We highly recommend this for private vehicle owners. A comprehensive car insurance policy covers third-party liabilities plus accidental damage to your own vehicle, regardless of who is at fault. If your car is relatively new or still under a bank hire-purchase loan, your bank will make this coverage mandatory.
The Checklist: How to Compare Car Insurance Like A Pro
When it’s time to renew, the lowest premium may not always offer the coverage that best suits your needs. Here is what you should check when you compare car insurance policies side-by-side:
Market Value vs. Agreed Value
Are you insuring your car for what it's currently worth (Market Value) or a locked-in price (Agreed Value)? Agreed Value protects you against drastic vehicle depreciation in the event of total loss or theft.
Essential Add-Ons (Special Perils)
Standard policies in Malaysia do not cover damage from floods, landslides, or fallen trees caused by convulsion of nature. Given our tropical weather, adding "Special Perils" coverage is highly advisable.
E-Hailing Usage
Are you using your car for Grab or other e-hailing services? Standard private car policies will void your claim if you get into an accident while carrying fare-paying passengers without the proper e-hailing add-on.
Approved Repairers
Check if the insurer has a wide network of reliable panel workshops.
How to Lower Car Insurance Premiums Safely
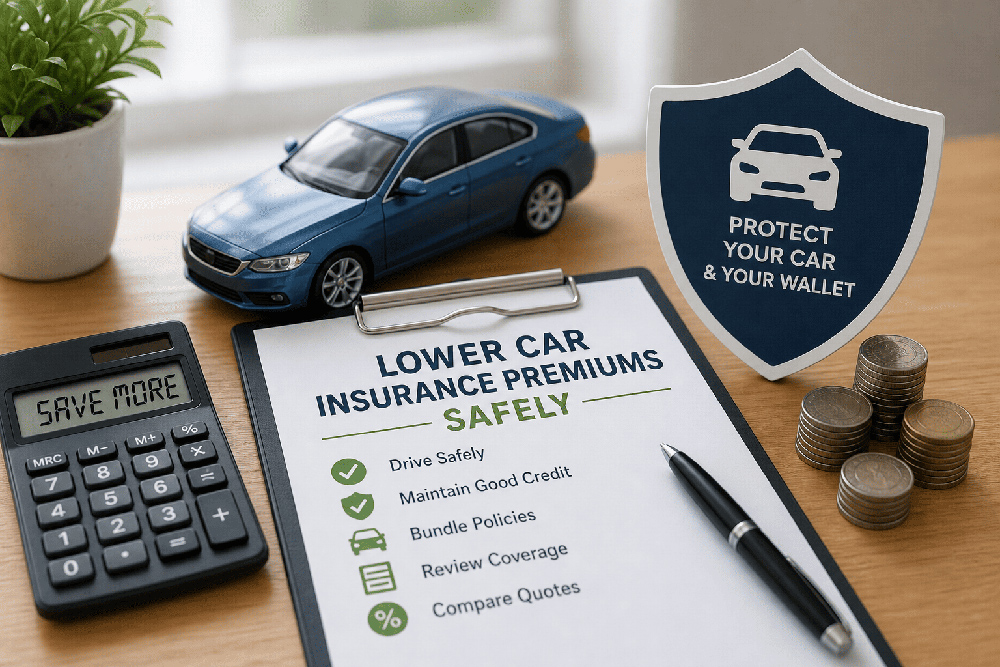
Everyone wants to save money, but you shouldn't do it by sacrificing essential coverage. If you are wondering how to lower car insurance premiums while maintaining suitable protection, follow these practical tips:
- Protect Your NCD: Your No Claim Discount (NCD) is your biggest money-saver. Drive safely and avoid making trivial claims. Over five claim-free years, your NCD can build up to a massive 55% discount on your premium.
- Consider a Voluntary Excess: If you agree to pay a "voluntary excess" (e.g., the first RM500 of any claim you make), your insurer will often lower your upfront premium. This is a smart move if you are a very safe driver.
- Install Security Devices: Some insurers offer premium discounts if your car is fitted with approved anti-theft devices, telematics, or even dashboard cameras.
- Never Under-Insure: It might be tempting to declare a lower value for your car to get a cheaper premium. Don't do it! If you under-insure your vehicle, the "Average Clause" will be applied during a claim, meaning the insurer will only pay out the same proportion of your sum insured against the actual value.
Conclusion
The right insurance coverage is your best defense on the road. Take the time to request quotes from multiple insurers, review the fine print, and understand exactly what you are paying for.
Want to learn more about the claims process or how your NCD works? Visit our main Motor Insurance Consumer Guide
Frequently Ask Questions | FAQ
Can I upgrade from Third-Party to Comprehensive car insurance at any time?
You can only change your coverage type when it is time to renew your policy. However, if you recently paid off your car loan and wish to downgrade, you must wait until your current comprehensive policy expires. It is always best to consult directly with your insurer or agent.
Does my comprehensive car insurance cover flood damage?
No. Standard comprehensive policies in Malaysia do not cover "Acts of God" or natural disasters. To be protected against floods, you must purchase the "Special Perils" add-on when renewing your policy.
Will I lose my NCD if I claim for a broken windscreen?
If you purchase a "Windscreen" add-on cover, you can claim for a shattered or cracked windscreen without losing your accumulated NCD. If you do not have this add-on and make a claim for the glass, your NCD will drop back to 0%.
About PIAM:
Persatuan Insurans Am Malaysia (PIAM) originated from the establishment of various insurance and tariff associations set up in 1885 that played a role as a collective voice of the insurance industry. In June 1961, the Insurance Association of Federation of Malaya was formed to maintain tariff insurance legislations and promote sound insurance practices. For the first time, an Association was established in Kuala Lumpur to safeguard the country's general insurance interest. Subsequently, PIAM was established in May 1979 as a statutory trade association recognised by the Government of Malaysia for all registered insurance business.